Schools
52% of Hong Kong’s underprivileged children spend over 2 hours a day on devices
By Marcus Chen
Advertisement · Why this ad?
Katherine oversees editorial operations across all six brands. Before joining The Meridan Group, she spent 14 years at the Minneapolis Star Tribune, where she led the metro desk through its digital transformation. She holds a Master's in Journalism from Northwestern's Medill School.
More from Katherine →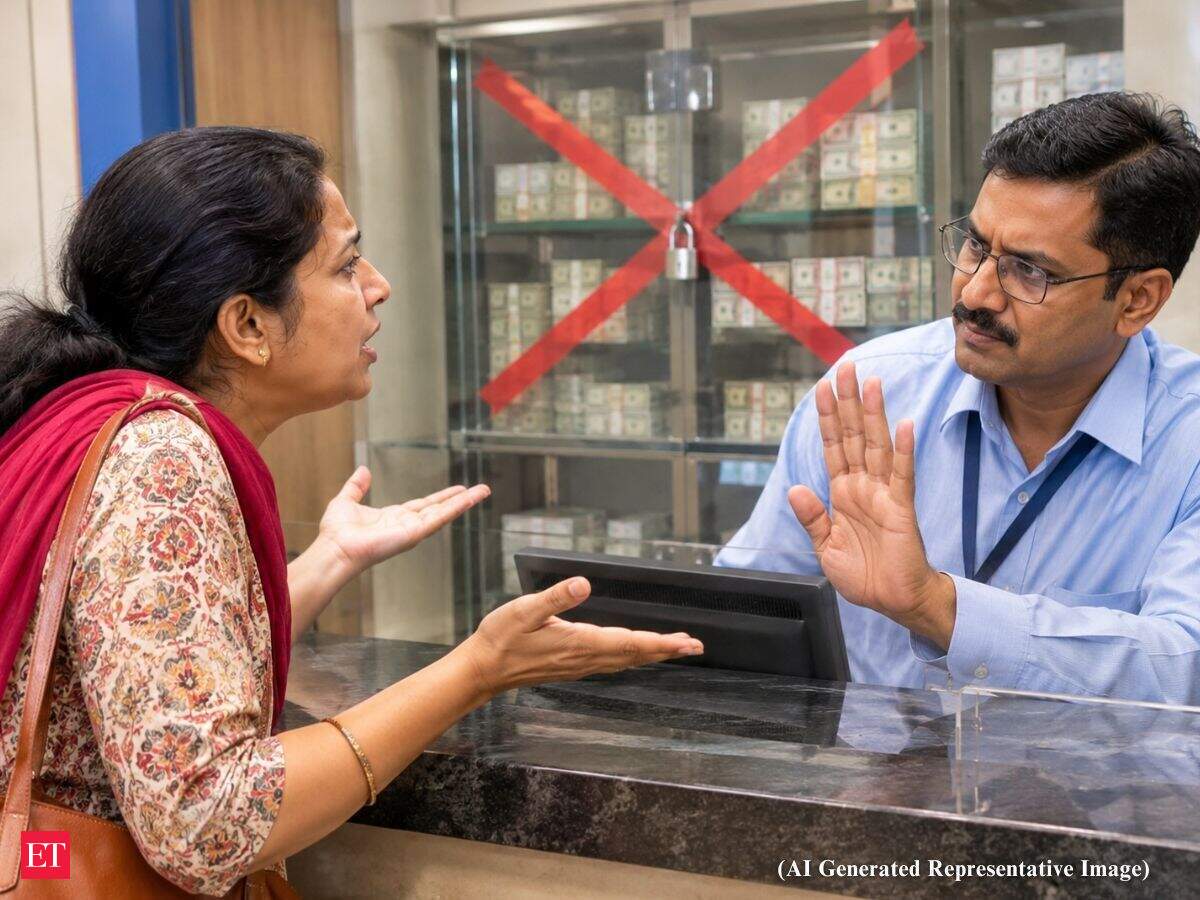
The promise of a 12% return on fixed deposits, a seemingly straightforward path to financial security, turned into a protracted ordeal for two Bangalore residents, culminating in a recent order from the Gadag District Consumer Disputes Redressal Commission. The case highlights the vulnerability of depositors when financial institutions fail to uphold their commitments, and underscores the importance of diligent oversight within community-based lending organizations. One woman found herself unable to access her Rs 9.5 lakh investment, while a 73-year-old senior citizen was left awaiting a matured fixed deposit of Rs 5 lakh, both victims of a Karnataka credit society’s inability to meet its obligations.
The situation arose from investments made with Kittur Rani Chennamma Urban Credit Souhardha Sahakari Ltd. Two customers, a woman and a senior citizen, deposited a total of Rs 17.63 lakh across various accounts, including fixed deposits, savings accounts, and a recurring deposit. The woman’s investment included two fixed deposits: one worth Rs 5 lakh carrying an annual interest rate of 10.80% and maturing on November 10, 2025, and another worth Rs 4.5 lakh with a promised 12% annual interest. The senior citizen held a savings account balance of Rs 4,79,099 and a recurring deposit of Rs 76,500, in addition to a matured fixed deposit. The total amount stuck across these various accounts amounted to Rs 17.63 lakh.
When the customers sought repayment, they were met with silence. Their demands remained unfulfilled, extending beyond the maturity date of the fixed deposits and impacting their savings and recurring deposit balances. Frustrated by the lack of response, they sent a legal notice to the society on February 4, 2026, formally requesting the return of their funds. The subsequent legal proceedings revealed a systemic failure on the part of the credit society to honor its financial commitments to its depositors.
During the consumer commission proceedings, the customers presented documentation including fixed deposit receipts, savings account passbooks, and a recurring deposit passbook, alongside the legal notice and postal records confirming their attempts to recover their funds. The society attempted to deflect responsibility by citing proceedings under the Karnataka Protection of Interest of Depositors in Financial Establishments Act, arguing that the consumer proceedings should be halted. However, this objection was rejected by the commission, which noted that the society had not provided evidence to support this claim. The Law Commission of India often addresses issues of financial protection for depositors.
The Gadag District Consumer Disputes Redressal Commission ultimately ruled in favor of the customers, finding that the society had failed to provide evidence demonstrating repayment or withdrawal of savings account balances. The commission emphasized the obligation of financial institutions to return fixed deposit amounts with interest upon maturity and savings balances when requested. The failure to do so, despite repeated demands and a legal notice, constituted a deficiency in service. The commission directed the society to repay a total of Rs 17,63,274, with varying interest rates applied to each account type, reflecting the time period over which the funds were held. The detailed breakdown of the amounts owed is as follows: Rs 2,57,675 for the first customer's savings account; Rs 5,00,000 for a fixed deposit; Rs 4,50,000 for the second fixed deposit; Rs 4,79,099 for the second customer’s savings account; and Rs 76,500 for the recurring deposit. The Reserve Bank of India regulates financial institutions and strives to maintain stability in the banking sector.
The commission outlined specific interest rates for each account to ensure fair compensation for the delayed repayment. The Rs 5 lakh fixed deposit will carry 10.80% annual interest until its maturity on November 10, 2025, followed by 7.5% interest on the maturity amount until repayment. The Rs 4.5 lakh deposit will carry 12% interest from November 15, 2024, until February 4, 2026, followed by 7.5% interest until realization. The savings account balances will carry 2.5% annual interest from February 4, 2026, while the recurring deposit balance will carry 6% interest from that date.
This case serves as a stark reminder of the risks associated with entrusting one’s savings to smaller, community-based financial institutions. While these organizations often play a vital role in providing access to credit for underserved populations, they are not immune to financial difficulties or mismanagement. For families in Bangalore, particularly senior citizens and those on fixed incomes, such losses can be devastating, eroding their financial security and impacting their ability to meet essential needs. The stability of families is intrinsically linked to the security of their finances; unexpected losses can strain relationships and create significant hardship. The importance of careful due diligence when choosing a financial institution cannot be overstated. Families need to understand the risks involved and ensure that their savings are protected.
The story of these two Bangalore residents is more than just a legal dispute; it’s a reflection of a broader challenge facing our communities. While credit societies can be valuable resources for those seeking financial services, they also carry inherent risks. The failure of Kittur Rani Chennamma Urban Credit Souhardha Sahakari Ltd. to honor its commitments underscores the importance of robust oversight and transparency within these institutions. It's a sobering reminder that the promise of higher returns often comes with increased risk, and that even seemingly stable organizations can face financial difficulties. The commission's order is a victory for those who have been wronged, but it also raises important questions about the regulation and supervision of smaller financial institutions. We must ask: What safeguards can be put in place to protect depositors? How can we ensure that these organizations operate with integrity and accountability? And how can we better educate families about the risks involved in investing their hard-earned savings?
The credit society has been ordered to repay the full amount of Rs 17,63,274, including interest, within eight weeks. The commission’s decision highlights the crucial role of consumer protection laws in safeguarding the interests of depositors. This case should serve as a cautionary tale for other credit societies and financial institutions operating in Karnataka and beyond. It is imperative that these organizations prioritize the security of depositors' funds and operate with transparency and accountability. The National Consumer Helpline provides resources and assistance for consumers facing disputes with businesses.
The ruling also emphasizes the importance of residents exercising caution when choosing where to invest their savings. While the promise of higher interest rates can be tempting, it is essential to thoroughly research the financial stability and reputation of any institution before entrusting them with one’s money. Families should be encouraged to seek financial advice from trusted sources and to diversify their investments to mitigate risk. The Financial Planning Association offers resources and guidance for individuals seeking financial planning assistance.
The Gadag District Consumer Disputes Redressal Commission’s order, pronounced on October 22, 2026, by President Shri A. G. Maldar and Member Dr. Manjunath M. Bammanakatti, provides a measure of justice for the affected customers. The commission also awarded Rs 20,000 compensation for mental agony and Rs 5,000 towards litigation costs. The incident serves as a broader call for vigilance and reform within the financial sector, ensuring that the promise of financial security does not become a false one. The Bangalore City Municipal Corporation plays a role in ensuring the overall well-being of the city's residents, including their financial security.
Moving forward, it will be important to monitor the society’s compliance with the commission’s order and to assess the impact of this case on other credit societies in the region. Ongoing efforts to strengthen consumer protection laws and promote financial literacy among residents are crucial. The resilience of families and communities depends on informed decision-making and responsible financial practices. India Education provides resources for financial literacy and economic development.
This situation serves as a poignant reminder of the importance of financial prudence and the need for robust regulatory oversight to protect vulnerable individuals and families. The long-term effects on the affected customers remain to be seen, but the commission’s decision offers a measure of redress and serves as a deterrent against future misconduct. It is our hope that this case will inspire greater vigilance and accountability within the financial sector, ensuring that the promise of financial security remains a reality for all.
By Marcus Chen
By Katherine Langford
By Katherine Langford
By Katherine Langford